
Money Needed in the UAE
Dirham savings may already cover school fees due next year. Your plan includes living costs, loan repayments and emergency savings. If Indian funds must cover payments, fund values and exchange rates affect available dirhams.
Build Your India Wealth Plan From Dubai
Investing in Indian mutual funds from the UAE starts with reviewing your finances. At Clarity Financial Consultancy, we review your mutual funds, bank deposits and UAE assets alongside the wealth you already hold in property. We assess your income, retirement goals and expenses in rupees or dirhams.
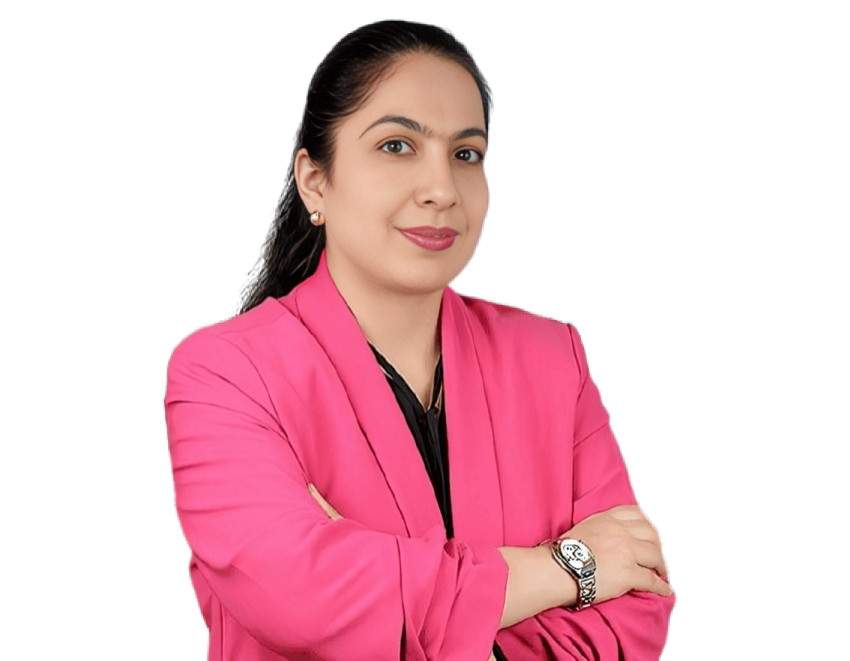
Dr Rafiya Mushtaq
Founder · MBA · ICWIM (CISI)
Send an enquiry
Dr Rafiya Mushtaq
Founder of Clarity Financial Consultancy · MBA · ICWIM (CISI)
Prefer to write? Send an enquiry.
Your investment plan starts with the money you need in each country. We review how Indian mutual funds for NRIs could fund your future expenses.
Dirham savings may already cover school fees due next year. Your plan includes living costs, loan repayments and emergency savings. If Indian funds must cover payments, fund values and exchange rates affect available dirhams.
Rental income can pay part of your monthly support for parents. For education or retirement, account for income, savings and investments allocated to those expenses. Before discussing a SIP for NRI investors, check your monthly savings after expenses and repayments.
We compare costs, payment dates and currencies across the countries you are considering. Education outside India or the UAE may require another currency.
Dr Rafiya Mushtaq
Founder of Clarity Financial Consultancy · MBA · ICWIM (CISI)
Prefer to write? Send an enquiry.
Investing in Indian mutual funds from the UAE starts with reviewing your finances.

Our UAE–India investment planning checks how much money you can access and invest. At Clarity Financial Consultancy, we assess income, savings, investments and loans. We also include any existing provident fund or pension savings.
Your estimated property values and outstanding loans help establish how much wealth you hold in property. Property values are separate from cash available for investment. This review does not include property advice, property investment recommendations or property services. We exclude household expenses, personal loan repayments and emergency savings when assessing money available to invest.
Currency conversion affects the dirham amount available from your Indian investments.
Exchange rates are hypothetical; figures exclude tax and charges.
Compare the dirham amount with your UAE payment.
We separate business working capital from your personal investable wealth before discussing investment amounts. Money required for salaries, suppliers, repayments and operations remains available to the business. Together, we review what is available to you personally after household expenses, loan repayments and emergency savings.
Your India Wealth Map is the written plan from Dr Rafiya Mushtaq for UAE–India NRI review. We discuss the reason for each proposed change before you approve it.
Before booking, we explain the review process, applicable fees and when you will receive your India Wealth Map.
Your India Wealth Map lists the investment amount and when you need the money. We review the risks in your existing mutual fund portfolio and explain how they relate to your goals, time horizon and currency needs.
We consider whether a fall in value could leave you short of money for an expense and discuss the level of risk you are comfortable accepting.
Our review can include funds bought through another bank or investment platform. We compare fund charges and the amounts held in shares, bonds and other assets, then assess how proposed purchases would change those amounts.
Different funds can hold shares in the same companies. Several holdings may also depend on one industry. Funds can also hold bonds from the same company or government.
You may be able to add money to an existing fund. We assess what a new fund would add before recommending another holding.
Suppose your two fund holdings are worth ₹20 lakh and ₹10 lakh. These figures are hypothetical. One company makes up 10% of the first fund and 5% of the second.
₹20 lakh × 10% + ₹10 lakh × 5% = ₹2.5 lakh.
Your holding in that company through both funds: ₹2.5 lakh, or 8.33% of their combined value.
The calculation covers one company across two funds. That percentage alone is insufficient reason to sell either fund.
We review what a proposed first mutual fund would add to investments you already own. Once the fund is agreed, we discuss how to spread your payments.
A SIP for NRI investors schedules regular mutual fund purchases. With a lump-sum purchase, you invest the agreed amount at once. You can make monthly purchases and invest a bonus in the same fund.
Before any sale or switch, we review purchase dates and possible exit charges, and identify tax questions for a qualified tax adviser.
Before you invest, we explain the partner name, service terms and charges. We clarify who recommends funds, submits your approved instructions and processes purchases.
We check whether the fund and platform can accept your investment, including citizenship, country of residence and tax-residency details.
We review whether your PAN, identity and overseas address details are current for Know Your Customer (KYC) checks. We identify the required tax-residency declarations and confirm with the platform which Non-Resident External (NRE) or Non-Resident Ordinary (NRO) account can fund a purchase and which registered account can receive withdrawals.
We explain the fund name, Direct or Regular plan, and Growth or IDCW option. You approve the investment amount, disclosed charges and payment instructions before submission. For regular purchases, we confirm the amount, frequency and start date with you.
Follow the official bank and platform payment instructions. Clarity Financial Consultancy does not hold your investment money.
We help you compare the fund name, plan, option and amount with the purchase confirmation and check the units shown in your investment statement. An application receipt or bank debit alone cannot confirm that you received fund units.
For a SIP, we help you check acceptance of the payment schedule and the first purchase separately. If a request is pending or rejected, the support team listed in your service details can use the transaction reference to explain the reason and next step. If money has left your account, we help you identify the payment receipt or refund status to check.
We treat transfers of existing investments as a separate decision and clarify whether a change transfers your units or requires selling and buying again.
We plan NRI mutual fund withdrawals around your retirement spending or education fees, starting with the expense amount, payment date and currency.
We include rent after costs, deposit interest or maturity proceeds, and pension payments. The plan counts only money available before the payment date and excludes money needed for other expenses.
We review where your investment money comes from and whether you may need to send proceeds from these investments to the UAE before discussing the account type.
Before submitting your mutual fund application
If you invested before relocating, read Indian Mutual Funds After Moving to the UAE for the account and investor-detail updates to check.
For expenses in India, we check when the withdrawal is expected to reach your registered account. For spending in the UAE, we identify the separate bank transfer you would need to arrange.
A Systematic Withdrawal Plan (SWP) sells units at regular intervals. Each withdrawal reduces the number of units you own. Payments can include money you originally invested. An SWP cannot guarantee income for life.
If you retire in another country, we reassess your expenses and spending currencies, including which account should receive withdrawals and what transfers you may need.
Many NRIs who contact us already hold Indian mutual funds, insurance-linked plans or pension products. Their question is not “what should I buy?” but “am I on track?”
A second-opinion review checks your existing holdings against your goals, timeline and currency needs. It does not assume you need anything new. For a broader review of your NRI finances, see our NRI Financial Advisor Dubai guide.
Each agreed NRI portfolio review compares current investments with the previous India Wealth Map. We check which approved purchases or sales still need completing.
If your family may need to locate or access these holdings, our NRI estate planning in Dubai guide explains how asset records, nominations and specialist legal advice fit into UAE–India planning.
What Changed
We discuss changes in income, loan payments, expense amounts and your retirement country. We also check how soon you need the money, even if the expense amount remains unchanged.
We account for money added and withdrawn when reviewing investment performance. Adding money can increase your balance even when investments lose value.
What Follows
We explain which investments you may be able to retain and the reasons for any proposed changes. A lower income could change future investment amounts without requiring a sale. You approve each proposed purchase or sale before submission through the partner platform.
We agree the review schedule, any additional review arrangements and fees in advance, and explain what written follow-up the service includes.
You discuss your UAE and Indian finances with Dr Rafiya Mushtaq, founder of Clarity Financial Consultancy. She personally leads the review. Together, you review your India Wealth Map and the reasons for any proposed investment changes.
Qualifications: MBA; International Certificate in Wealth & Investment Management (ICWIM) from the Chartered Institute for Securities & Investment (CISI).
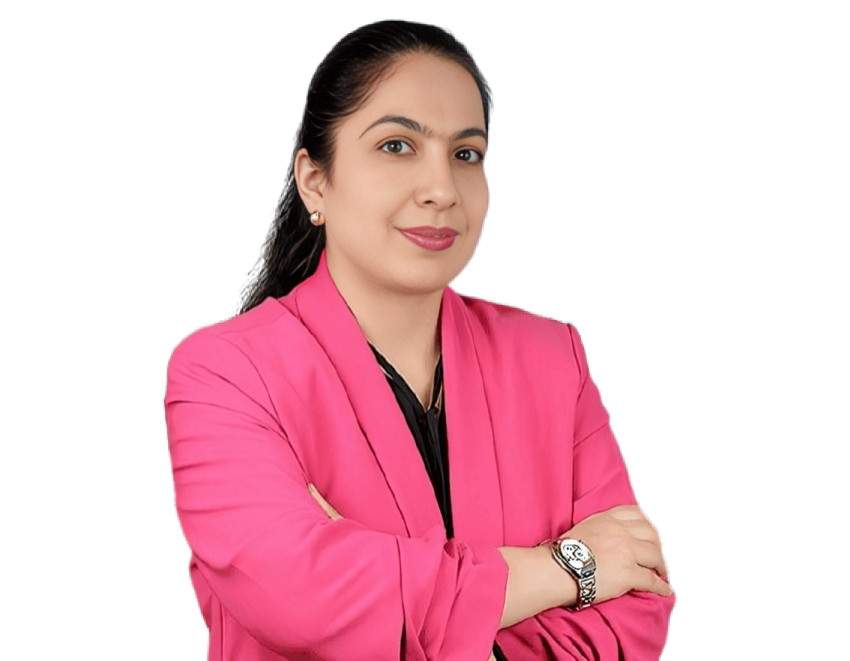

The services provided were exceptionally good. Dr. Rafiya Mushtaq and her colleagues are one of the best financial advisors in
Read full testimonialI strongly recommend Rafiya What a refreshing difference to past experience with other financial consultants, she did not try to
Read full testimonialProvided me a tailor made solution "Appreciate the fact that Rafiya takes the time to get to know what is
Read full testimonialYour first enquiry can focus on what you want to discuss. Please do not send identity documents or account numbers at this stage.
The following documents and details help us prepare for the meeting. Estimates can be labelled as such.
If a statement is missing, we can still discuss the investment during the meeting, including holdings through other banks or platforms.
Before booking, we explain how the meeting takes place, what the fee covers, when you will receive your India Wealth Map and whether any work is charged separately.
During the meeting, we review how your UAE and Indian finances affect investment decisions and identify any missing statements or figures needed.
Your written action plan, the India Wealth Map, sets out the findings and agreed next steps. We explain the reasons for proposed changes and agree who will complete each task.
Any purchase or sale through the authorised partner platform requires your approval. We explain which follow-up reviews the fee includes and any charges for additional reviews.
Yes. Your chosen fund company and platform must accept your citizenship and residency details. Complete the required identity checks and tax-residency declarations before investing. Confirm which NRE or NRO account the platform accepts for payment.
You can hold many mutual funds without a demat account. Your fund statement lists the units you own. Confirm that the platform supports this option. Exchange-traded funds (ETFs) require a demat account.
Yes. You can discuss investments you already own without committing to another purchase. Retaining existing investments can be the outcome.
Check your status on the official website of your KYC Registration Agency (KRA).
No. IDCW stands for Income Distribution cum Capital Withdrawal. A payout reduces the value of each unit, called NAV. It can include part of the money you invested. Neither the payout amount nor payment on a scheduled date is guaranteed.
A Systematic Withdrawal Plan (SWP) sells units to fund each payment. When each unit is worth less, a fixed withdrawal requires selling more units. Continuing those withdrawals can use up your investment sooner.
No. You arrange tax filing separately with a qualified tax professional. You submit money-transfer instructions to your bank. During the review, discuss which tax and banking checks you need before proceeding.
This page is for general information only and does not constitute tax, legal or accounting advice.
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully.
Clarity Financial Consultancy does not hold client investment money. Where applicable, investment implementation is completed through the relevant authorised partner/platform, subject to eligibility, KYC requirements and applicable regulatory requirements.
Any investment decision should be based on the client’s individual circumstances, objectives, risk profile and time horizon. Past performance does not guarantee future results.
Tax, residency, repatriation and regulatory rules in India and the UAE may change. Clients should obtain advice from an appropriately qualified tax or legal professional where required.